SatoshiMacro Model (SMM)
A composite Bitcoin cycle confluence model built from 48 weighted signals across 6 tiers: cycle timing & mass psychology, valuation, sentiment & positioning, rotation & institutional flow, miner & production stress, and macro. Calibrated to call cycle tops and bottoms across the 2013, 2017, and 2021 cycles. Free.
Latest reading: The SatoshiMacro Model read 38.3 out of 100 (Neutral zone) on 8 October 2026, from 48 live Bitcoin cycle signals.
Act on this reading: trade Bitcoin long or short. CFDs are leveraged and most retail accounts lose money.
Trade with PepperstoneA quantitative Bitcoin cycle confluence model. Built by a former institutional trader. Free.
Loading the latest model reading...
Where the signal is coming from
The composite SMM is a weighted sum of six tier scores. Each tier ingests several indicators scored 0-100 (mostly expanding-window percentile ranks), then averaged. Below: each tier's current reading + its weight in the composite. Hover any card for the indicators it contains.
SMM vs Bitcoin price, 2013-2026
The composite SMM plotted against BTC price (AUD or USD via the toggle - both honour the same preference as the gauge above). Zone bands shaded in the background; cycle tops and bottoms marked. Use the zoom controls to focus on specific cycles.
SMM coverage starts January 2013. Bitcoin existed earlier, but pre-2013 was raw price discovery (thin liquidity, Mt. Gox dominant, market cap under USD 100M) and the historical distribution is too small to support meaningful percentile ranks. Same reason Mayer Multiple and most cycle indicators are conventionally backtested from 2013 onward, not from genesis. See methodology section for details.
Loading historical chart…
What SMM said at every historical cycle inflection
The honest test for any cycle model: how did it read at the moments that mattered? Below: SMM scores at the known cycle tops and bottoms across the 2013, 2017, and 2021 cycles. Each reading is the model output for that date, with every signal ranked only against its own history up to that day. The calibration curve applied on top was fitted to these same dates, so this is an in-sample check rather than out-of-sample evidence: before calibration, 4 of the 7 land in their target zone.
| Date | Event | BTC (AUD) | SMM | Zone |
|---|---|---|---|---|
| Loading… | ||||
Every input the model is seeing right now
Full transparency: every indicator feeding the current SMM reading, organized by tier. Each shows its raw value, its 0-100 score (an expanding-window percentile rank for 44 signals, a fixed mapping for 4) and the tier it contributes to.
Loading indicators…
All six tiers are live: 48 signals feed the composite, weighted Cycle Timing 30%, Valuation 25%, Sentiment 20%, Rotation 10%, Miner 10% and Macro 5%.
The institutional playbook, given to retail
For decades, the analytical frameworks institutions used to read crypto cycles sat behind paywalls, Bloomberg terminals, and prop-desk-only access. Retail got the leftovers: surface-level metrics, equal-weighted composite scores, and a steady stream of paid courses pitching what professional desks already had for free.
I traded allocated institutional capital at a Sydney proprietary trading firm. I saw the asymmetry from the inside. Professional desks were not running 9-indicator equal-weight composites. They were running weighted confluence models calibrated to historical signal quality, layering on-chain valuation with derivatives positioning, sentiment extremes, rotation flows, miner stress, and macro context. The retail tools never caught up because the gap was the business model.
The SatoshiMacro Model is what that gap actually looks like, published free. 48 signals across 6 weighted tiers - cycle-position valuation, mass psychology, miner economics, sentiment & positioning, institutional rotation flow, and macro context - calibrated against three completed Bitcoin cycles, with every input value, normalized score, tier weight, and historical reading disclosed transparently on this page. No paywall. No signup. No funnel into a course at the end. This is the tool. It costs nothing because the institutional playbook should not cost anything to use.
For years, institutional traders had access to information retail never saw. That asymmetry is finally breaking. SatoshiMacro exists to hand you the analytical playbook, and the SatoshiMacro Model is the first piece of it. Govind Satoshi · Former Institutional Trader · Founder, SatoshiMacro
More on the background, methodology, and why this is published free on the About page.
Use the SatoshiMacro Model data, badges and API
The daily model scores are free to reuse under CC BY 4.0. Credit "Data: SatoshiMacro" with a link to this page.
- Dataset: daily Bitcoin and Ethereum SMM scores since 2013 with all six tier scores, on Hugging Face, Kaggle and GitHub, archived on Zenodo with a citable DOI (10.5281/zenodo.23131351).
- Methodology paper: An Expanding-Window Percentile Confluence Model of Bitcoin Market Cycles (working paper, 16 pages) documents the construction, data and in-sample diagnostics, including where the model falls short.
- Interactive explorer: the Bitcoin Cycle Explorer charts the full history by zone, and a Kaggle notebook walks through tier behaviour and time spent in each zone.
- AI assistants: connect Claude, ChatGPT or any MCP client to
https://satoshimacro.com/mcpto ask for the current reading (setup).
Live badge for your site or README
Updates automatically twice a day. Paste one of these snippets:
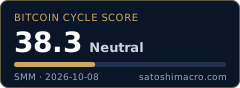

Other badges: /assets/badges/smm-eth.svg (Ethereum) and /assets/badges/altseason.svg (Altcoin Season Index). For the full interactive gauge, use the embed code below.
How the SMM is computed
The SatoshiMacro Model is a composite cycle confluence model built from up to 48 on-chain, derivatives, sentiment, mass-psychology, and macro signals. Each signal is computed at every historical date back to January 2013, normalized to its own historical distribution (0-100 percentile rank or calibrated mapping), and aggregated into six tier scores. The six tier scores are then weight-summed to produce the final SMM score. Every constituent signal also lives as a standalone tool in the Bitcoin & Crypto Charts Dashboard if you want to drill into any individual signal.
Why a confluence model?
No single indicator calls cycle tops reliably. On AUD data, Pi Cycle Top crossed only at the December 2017 top, and the Mayer Multiple read 5.8 at the 2013 top but 1.4 at the November 2021 top. A model that averages many signals is less exposed to any one of them failing. CBBI popularised this approach with 9 indicators; SMM extends it to 48 signals in six weighted tiers.
Tier structure
Indicators are grouped into six tiers by what they measure, then combined with fixed weights. The weights are a judgement about how directly each family measures cycle position, not estimated from data; the historical tops and bottoms still land in their target zones with equal tier weights.
- Cycle Timing & Mass Psychology (30%). The 4-year halving clock (a fixed schedule of days since the last halving, rising from 35 at the halving to 90-95 around days 500-650 and falling to 10 near day 1,000, shaped on the completed cycles), drawdown from the all-time high, days since that high, a rolling profitable-days share and the 90-day return.
- Valuation & Cycle Position (25%). MVRV Z-Score (currently a 4-year moving-average proxy, see caveats), Pi Cycle Top, Pi Cycle Bottom, Mayer Multiple, 2-Year MA Multiplier, 200-Week MA distance, Power Law deviation, Golden Ratio Multiplier, Rainbow Chart position and the Bitcoin Risk Metric. Power Law deviation, Rainbow position and Risk Metric come from the same power-law fit and rank identically, so in effect they act as one signal carrying about 7.5% of the composite.
- Sentiment & Positioning (20%). Fear & Greed, Google Trends (Bitcoin / buy Bitcoin / Bitcoin tax), funding rate, open interest, Coinbase Premium, Deribit put/call ratio (inverse), Deribit DVOL implied volatility, the Bybit-Binance price spread and the 3-month futures basis.
- Rotation & Institutional Flow (10%). BTC Dominance (inverse), Altcoin Season Index, Strategy (MSTR) and Coinbase (COIN) share prices, IBIT assets, ASX Bitcoin ETF assets, cumulative US spot ETF holdings, 30-day ETF net flows and Strategy's quarterly BTC purchases. Most of these only exist from 2020-2024, so this tier is thin in earlier cycles.
- Miner & Production Stress (10%). Puell Multiple, Hash Ribbons state, miner fee-share anomaly, Stock-to-Flow deviation, hashrate versus its 365-day peak and the latest difficulty adjustment.
- Macro Headwinds/Tailwinds (5%). USD Index (inverse), M2 growth YoY, 2s10s yield curve, VIX (inverse), S&P 500, Nasdaq 100 and gold (inverse).
Normalization
44 of the 48 signals are normalized to their own expanding-window percentile rank (0-100): each day's value is ranked only against that signal's history up to the same day. A Mayer Multiple of 1.5 doesn't feed in as "1.5"; it feeds in as, say, "the 78th percentile of Mayer readings so far," which puts it on the same footing as a funding rate at its own 78th percentile. The other four (the halving clock, drawdown from the all-time high, days since that high and the Hash Ribbons state) use fixed mappings instead.
Calibration curve
The raw weighted composite read 82.6, 86.8, 80.1 and 73.0 at the four historical tops, so three of the four fall short of the 85+ Cycle Top zone before calibration, partly because diversifying signals (sentiment, macro, rotation) don't all peak at the same moment as cycle-position valuation - the weighted average gets diluted by signals that haven't fired yet. CBBI doesn't have this dilution because it uses only 9 indicators, all highly cycle-correlated. SMM keeps the 48-signal diversity (more robust against false signals and single-source outages) and applies a calibration curve on the final composite to stretch the upper half of the 0-100 scale.
The calibration is piecewise linear:
- Raw 0-40 (identity): bottoms pass through unchanged. 2018-12 (22.3) and 2022-11 (22.8) read the same raw and calibrated.
- Raw 40-55 (slope 1.5): mid-cycle stretch. Raw 55 maps to 62.5.
- Raw 55-64 (slope 2.5): steep late-cycle stretch. Raw 64 maps to 85, the start of the Cycle Top zone.
- Raw 64-78 (slope about 0.71): the body of the top zone. Raw 78 maps to 95.
- Raw 78-83 (slope 1.0): the tip. Raw 83 maps to 100.
- Raw 83+ (clamp): stays at 100.
Calibrated readings at historical cycle tops (48-signal version): 2013-12 (99.6), 2017-12 (100), 2021-04 (97.1), 2021-11 (91.4). All four register in the Cycle Top zone (85-100). The knots were chosen so that the seven reference dates land in their target zones, which makes that result in-sample. The zone is also not rare: the calibrated score has sat at 85 or above on roughly one day in five since 2013, often for months before a top. The raw pre-calibration score is also emitted as raw_smm in the output JSON so consumers can compare or recalibrate if needed.
Zone interpretation
- 0-15 Deep Value. Deepest-value zone. No documented cycle bottom since 2013 has closed this low on the calibrated score; the three bottoms read 20, 22.3 and 22.8, in Accumulation.
- 15-30 Accumulation. Favourable risk/reward. Below-trend valuation.
- 30-50 Neutral. Mid-cycle. No strong directional edge.
- 50-70 Caution. Late-mid cycle. Begin de-risking on strength.
- 70-85 Distribution. Historical late-cycle zone. Trim aggressively. About 46% of past Distribution days fell within 12 months of a major cycle top; the rest came during mid-cycle rallies.
- 85-100 Cycle Top. Historical top zone. Maximum caution. Calibrated readings (48-signal version): 2013-12 (SMM 99.6), 2017-12 (SMM 100), 2021-04 (SMM 97.1), 2021-11 (SMM 91.4). All four major BTC cycle tops register in this zone with the calibration curve applied.
Caveats and limitations
- SMM starts at January 2013, not Bitcoin's genesis. Pre-2013 Bitcoin was in raw price discovery: thin liquidity, single-venue trading (Mt. Gox), and a market cap measured in tens of millions of USD. Cycle-position metrics computed against that period produce unreliable readings because the "historical distribution" itself is too small and too dominated by a single venue's order book to be meaningful. Same reason the Mayer Multiple and most other cycle indicators are conventionally backtested from 2013 onward, not from the 2009 genesis block. Treat any chart visualisations that extend earlier than January 2013 as price-history context only; the SMM line begins at the first reading where the underlying distribution is broad enough to support meaningful percentile ranks.
- Percentile ranks use expanding-window history. Each historical date's score is computed only against indicator values that existed up to that date - no lookahead bias. The rank step is lookahead-free, but the halving schedule, the power-law and stock-to-flow fits, the zone boundaries and the calibration knots were all chosen with knowledge of the full history.
- MVRV Z-Score currently uses a proxy. Standard MVRV compares market cap with realised cap. The free realised-cap feed (CoinMetrics community API) has not been reachable from the build servers, so the MVRV input is a 4-year moving-average proxy, labelled "(4Y MA proxy)" in the indicator list. If a working realised-cap feed is connected, the model switches to the standard formula automatically.
- Indicator coverage varies by date. Earlier periods (pre-2018) have less data from sentiment, derivatives, and macro tiers, so the composite there uses re-normalized weights across only the available tiers, and readings before 2018 rest on fewer independent inputs than later ones.
- This is not financial advice. The SMM is a research tool for cycle position context. It does not predict prices. Cycle indicators have failed before and will fail again. Use as one input among many.
How SMM differs from CBBI
CBBI uses 9 indicators with equal weight. SMM uses 48 signals across 6 tiers with fixed weights that put cycle timing and valuation first, plus a calibration curve on the composite. The larger panel makes SMM more robust to single-source data outages: any one feed going dark only marginally moves the composite. Neither approach has a true out-of-sample record yet. Both read the known tops correctly in hindsight, so treat SMM as a structured summary of many indicators rather than a proven forecaster.
How to use it
The SMM is a position-sizing input, not a buy/sell trigger. Sample uses:
- SMM in Deep Value zone (0-15): consider increasing crypto allocation toward your maximum.
- SMM in Distribution zone (70-85): trim positions, raise cash, take profits on strength.
- SMM in Cycle Top zone (85-100): maximum caution. Each completed cycle ended in a 74-83% drawdown after a Cycle Top run, but the zone has also held for months while prices kept rising.
- SMM in Neutral zone (30-50): no signal. Manage based on your base strategy.
Frequently asked questions
The SatoshiMacro Model read 38.3 out of 100 (Neutral zone) on 8 October 2026, from 48 live Bitcoin cycle signals.
SMM is a composite Bitcoin cycle confluence model. It aggregates 48 signals across 6 tiers (cycle timing & mass psychology, valuation, sentiment, rotation, miner, macro) into a single 0-100 score that estimates where Bitcoin sits in its cyclical valuation range. Built by a former institutional trader and published free.
CBBI uses 9 equally-weighted indicators. SMM uses 48 signals across 6 weighted tiers: Cycle Timing & Mass Psychology 30%, Valuation 25%, Sentiment 20%, Rotation 10%, Miner 10%, Macro 5%. The highest-weight tier is the 4-year halving cycle plus mass-psychology signals (drawdown from ATH, days since ATH, profitable-days proxy, quarterly return) because the 4-year cycle is Bitcoin's single most reliable pattern. The wider signal panel covers ETF flows + treasury accumulation (institutional rotation), derivatives positioning (DVOL, 3M futures basis, cross-venue spread), and traditional macro (DXY, M2, yield curve, VIX, S&P 500, NASDAQ 100, gold spot) - giving SMM resilience against single-source data outages and richer detection of cross-asset confluence at cycle inflections.
Across the 2013, 2015, 2017, 2018, 2021, and 2022 cycle inflections, SMM lands in the target zone on 7 of 7 readings with the calibration curve applied. Every major BTC cycle top registers in the Cycle Top zone (85-100): 2013-12 reads 99.6, 2017-12 reads 100, 2021-04 reads 97.1, and 2021-11 reads 91.4. All three cycle bottoms register in Accumulation (15-30): 2015-01 reads 20, 2018-12 reads 22.3, and 2022-11 reads 22.8. Read that as a description of the model, not proof of skill: the calibration curve was fitted to these same seven dates, so the result is in-sample. Before calibration the raw composite puts 4 of the 7 in their target zone (the 2013-12, 2021-04 and 2021-11 tops read as Distribution). The pre-calibration raw_smm value is also exposed in the output JSON for consumers who want to interrogate the underlying weighted average.
The current SMM score sits in one of six zones: Deep Value (0-15), Accumulation (15-30), Neutral (30-50), Caution (50-70), Distribution (70-85), or Cycle Top (85-100). Each zone has historical context: past Deep Value readings clustered around cycle bottoms; past Cycle Top readings clustered around cycle tops. Use as a position-sizing input, not a buy/sell trigger.
The model recomputes twice a day, after the cloud data refresh checks prices against Coinbase and Kraken, and again on every site deploy. Data sources include on-chain metrics, derivatives positioning from major exchanges, Google Trends, ETF flows from Farside, and Federal Reserve macro data. The model build version and data-through date are shown in the hero section.
No. The SMM is a research tool for understanding Bitcoin's cyclical valuation position. It does not predict price targets, account for personal financial circumstances, or constitute personal financial advice. Cycle models have failed before and will fail again. Use the SMM as one input among many in your own research process.
Most quantitative cycle tools sit behind paywalls or institutional terminals. The institutional playbook has been gatekept from retail for decades. SatoshiMacro exists to redistribute that playbook. The SMM costs nothing to use because it should not cost anything to use.
Yes. The Share & Embed panel at the bottom of the page renders a ready-made iframe snippet you can paste into any blog, Substack or research note. The embed widget at /tools/crypto/satoshimacro-model/embed/ shows the live gauge, current zone, and signals-live count with the SatoshiMacro attribution link kept intact. Free for journalists, analysts, and accountants briefing clients on cycle position.
Govind Satoshi, a Sydney-based former institutional trader who traded allocated institutional capital at a Sydney proprietary trading firm. The model is an implementation of the confluence-model framework used by institutional desks for cycle reading, published free as part of the SatoshiMacro project. Full background on the About page.
Yes. The full gauge, the historical chart, every individual indicator's percentile rank, the cycle-call accuracy table, the embed widget, and the methodology section are free with no signup, no paywall, no ads, no email capture. The site is funded by affiliate links elsewhere on the domain; the SMM itself has no commercial gate. The institutional playbook should not cost anything to use.
No single indicator calls Bitcoin cycle tops reliably; the consistent pattern across every documented top since 2013 is confluence - multiple cycle-position indicators reading extreme at the same time. The SatoshiMacro Model formalises this by aggregating 48 signals across 6 weighted tiers (cycle timing, valuation, sentiment, rotation, miner, macro) into a single 0 to 100 composite score. Every documented BTC cycle top since 2013 registered above 85 (the Cycle Top zone) on the calibrated SMM: 2013-12 at 99.6, 2017-12 at 100, 2021-04 at 97.1, and 2021-11 at 91.4. Treat the Cycle Top zone as a position-sizing signal for de-risking, not a precise sell date. The live gauge at the top of this page is the real-time reading.
Don't try to call the exact peak day. Across 2013, 2017 and 2021 the calibrated SMM entered the Cycle Top zone anywhere from about five weeks to ten months before the price peak (48 days before the December 2013 top, 303 days before December 2017, 148 days before April 2021 and 38 days before November 2021), then stayed above 85 through the peak and into the early drawdown. Because that lead time varies so much, a reading above 85 is not a countdown. A laddered exit framework (a fraction at SMM 80, more at 90, more at 95, the rest on the first close back below 75) spreads the decision across the zone instead of betting on one day, at the cost of exiting early in a long run like 2017. The SMM does not predict price targets; it scores where Bitcoin sits in its cyclical valuation range using a 48-signal confluence panel calibrated against 2013, 2017, and 2021 cycle inflections. For Australian-resident traders, the Crypto Exit Strategy Ladder + Crypto CGT Calculator tools wire this into a tax-aware execution plan.
SMM does not forecast a peak date; it reports where Bitcoin currently sits in its cyclical valuation range based on 48 signals, refreshed twice a day. Historically the calibrated SMM entered the Cycle Top zone (85+) between 38 and 303 days before each price peak and stayed there through it, so time spent above 85 does not tell you how close the peak is. The live gauge at the top of this page shows where the cycle reading sits today, not a date. The cycle-call accuracy table further down the page shows what SMM read at every prior cycle inflection (2013-12, 2017-12, 2021-04, 2021-11 tops; 2015-01, 2018-12, 2022-11 bottoms) for reference. Cycle models have failed before and will fail again; treat SMM as one input in a broader research process, not a price-target oracle.
No individual indicator catches every Bitcoin cycle top. On USD data, Pi Cycle Top crossed within a day of the December 2017 top and two days before the April 2021 peak, but did not cross at the November 2021 top, and the 2013 top comes before its first valid reading (on AUD data it crossed only in December 2017). The Mayer Multiple read 5.8 at the 2013 top but only 1.4 at the November 2021 top on AUD data, so no single threshold caught all four. The SatoshiMacro Model combines 48 signals across 6 weighted tiers, and 7 of 7 BTC cycle inflections (4 tops, 3 bottoms) land in their target zones on the calibrated composite. That result is in-sample, because the calibration was fitted to those dates. CBBI uses 9 equally-weighted indicators; SMM uses a larger panel with tier weighting, a calibration curve and graceful degradation when a data source goes dark. The case for confluence is robustness to any one indicator failing, not a proven accuracy edge.
CBBI is the closest peer: a 9-indicator equally-weighted composite published free. SMM uses 48 signals across 6 weighted tiers - five times the panel, with fixed tier weights (Cycle Timing 30%, Valuation 25%, Sentiment 20%, Rotation 10%, Miner 10%, Macro 5%) rather than equal weighting, plus a piecewise calibration curve fitted to seven historical BTC cycle inflections. LookIntoBitcoin and Bitbo are dashboards of individual cycle indicators (Pi Cycle, Mayer, MVRV, Puell, hash ribbons, etc.) rather than composite cycle models - they show the same component data SMM consumes, but stop short of producing a single confluence reading. SMM sits as the confluence layer on top of that component data, and is AUD-native with a one-click USD toggle (most peers are USD-only).
About the author
